In recent years, the large amount of investment in the Polystyrene Industry (PS industry) was not able to exchange for the equivalent great profit. Instead, the balance of supply and demand for PS in the domestic market has been broken, which means the domestic PS industry is overcapacity and the pace of expansion need to slowdown in the future.
From 2012 to 2014, the newly added production capacity of PS industry is 800,000 tons, and the total capacity has reached a record high in 2014. But the growing speed of PS demanding is much lower than that of PS production, so the conflict of PS supplying and demanding has become obvious.
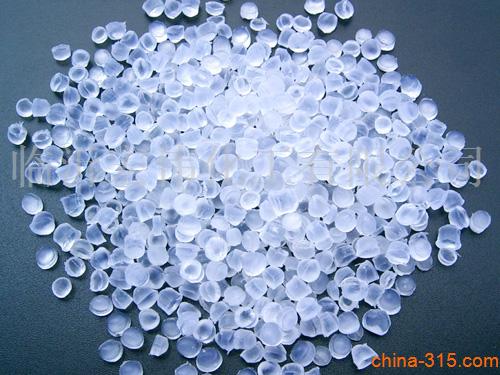
PS resins
The operating rate of the domestic PS industry in 2014 is 2% lower than that of 2013. The utilization speed of PS materials in the domestic PS products plants is comparatively slow and the inventory pressure is increased. The decline of PS production also reflects the weakness of domestic demand.
And the profit of the PS industry in 2014 also has decreased and is at the low point in the development history. In the first and fourth quarters, the EPS industry (Styrofoam industry)—a downstream industry of Styrene, is in the off-season and the Styrene is at a comparative low price, so Polystyrene has a higher a profit. However, in the second and third season, EPS production is the busy season and Styrene is at a high price. Then the Polystyrene industry’s margin is lower.
The current situation is that the production capacity of China’s PS industry is increased at the annual rate of 7%, closely following the growing speed of GDP, but the consumption speed has declined significantly. And the PS industry, especially the EPS production field has a tight connection with the development of EPS recycling business (Styrofoam recycling), which is about recycling and regenerating waste EPS materials into new valuable products with the equipment like Styrofoam Densifier.